A family gift can look settled for decades. The donor’s statement is recorded, the donee takes possession, the revenue record changes, and nobody raises a serious objection. Then an heir says the gift never happened at all.
That is the tension behind Gift Mutation in Pakistan and the Supreme Court judgment reported as 2026 SCMR 855, Mst. Addan (deceased) through L.Rs. v. Province of Sindh and others. The case does not make every old mutation untouchable. It shows what happens when a gift is supported by official record and long possession while the allegation of fraud remains vague and unproved.
The real questions are legal: Was there a gift, acceptance and possession? Was fraud proved? Was the correct relief claimed within limitation?
Table of Contents
Judgment at a Glance: Why This 1971 Gift Survived
| Point | What the Record Shows |
|---|---|
| Case | Mst. Addan (deceased) through L.Rs. v. Province of Sindh and others |
| Citation | 2026 SCMR 855 |
| Court | Supreme Court of Pakistan |
| Bench | Irfan Saadat Khan and Aqeel Ahmed Abbasi, JJ |
| Decision date | 1 October 2025 |
| Property | Agricultural land in Deh Deparja, Taluka Mirwah, Khairpur |
| Disputed record | Revenue Entry Nos. 33 and 34 dated 6 May 1971 |
| Gift entry | Sisters’ gift recorded through Entry No. 34 |
| Main challenge | Fraud, bogus entries and denial of gift |
| Delay | About 27 years before Suit No. 48 of 1998 |
| Supreme Court result | Appeals dismissed; High Court judgment maintained |
| Core lesson | Specific proof can defeat an entry; vague fraud cannot |
The appeals were decided on 1 October 2025; 2026 SCMR 855 is the reported citation.
IRAC: Why the Supreme Court Refused to Cancel the Gift
| IRAC | Court-Centred Explanation |
|---|---|
| Issue | Could the 1971 gift and revenue entries be treated as fraudulent and ineffective when challenged roughly 27 years later? |
| Rule | A Muslim gift requires declaration, acceptance and delivery of possession. Fraud must be specifically pleaded and proved. Limitation must be examined. Long-standing lawful revenue entries may carry evidentiary weight and statutory presumption. |
| Analysis | Jumo produced revenue record, donor statements, testimony and possession evidence. The challengers did not give specific particulars of fraud or convincing independent material. The lower courts also failed to decide the framed maintainability issue. |
| Conclusion | The Supreme Court found no basis to disturb the Sindh High Court judgment and dismissed both appeals. |
In Gift Mutation in Pakistan, the transaction behind the entry remains critical. The Supreme Court ultimately held that the appellants had failed to establish fraudulent gift and mutation.
Four Sisters, One Gift—and a Fight 27 Years Later
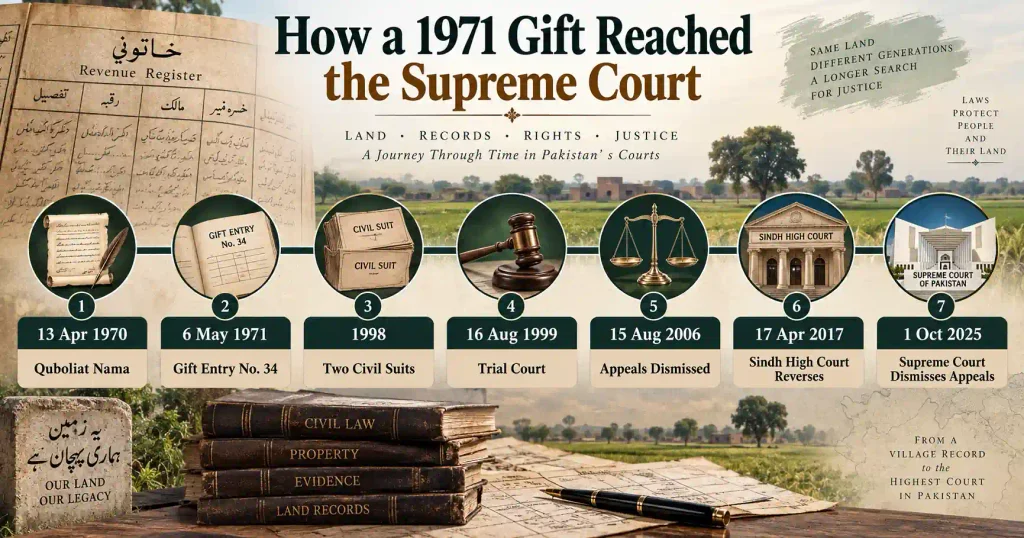
The dispute concerned Sher Muhammad’s family land. His son was Jumo alias Juman; his daughters included Mst. Addan, Mst. Koral, Mst. Makhan and Mst. Subhan Khatoon.
According to the record, the sisters gifted their shares to Jumo through Entry No. 34 dated 6 May 1971, recorded before the Mukhtiarkar in the presence of witnesses. The record also showed that Mst. Addan had received other land from Jumo through a Quboliat Nama dated 13 April 1970.
For Gift Mutation in Pakistan, Jumo’s later conduct mattered: he remained in possession, cultivated the land and paid land revenue. In 1998, he filed Suit No. 22 of 1998 for declaration and injunction.
Mst. Addan denied the gift and alleged fraud and collusion. About six months later, she filed Suit No. 48 of 1998 seeking declaration, joint possession, mesne profits and injunction.
First Trap: A Mutation Is Not Title by Itself
A major mistake in Gift Mutation in Pakistan is treating a mutation as though it independently creates ownership.
It does not.
A mutation is part of the revenue record. Courts may examine the original transaction behind it. If an alleged oral gift is not proved, the fact that a mutation was entered may not be enough.
In Gift Mutation in Pakistan, an old entry may carry weight when supported by donor statements, possession and consistent conduct. It is evidence of the claimed transfer, not a substitute for the transaction itself.
For the three ingredients of hiba and proof of oral transactions, readers can also review our guide on Oral Gift in Pakistan.
The Challengers Had a Serious Claim—but a Proof Problem
Mst. Addan’s side denied the gift, called the entries bogus and fraudulent, and argued that a female heir could not lose inheritance on an unsupported claim of surrender.
They also said Jumo had to prove the transaction behind the mutation. The Supreme Court did not say fraud can never defeat Gift Mutation in Pakistan; it held that this fraud allegation lacked the required particulars and convincing proof.
The appellants had specifically argued before the Supreme Court that once the mutation was challenged, the respondent relying on it was required to prove the original transaction. They also argued that an inheritance right could not simply be surrendered through an oral assertion in favour of a male family member.
Jumo’s Evidence Went Beyond the Mutation Entry
Jumo appeared as a witness, produced Ali Bakhsh as another witness and placed documentary material on record. The revenue record included donor statements and signatures or thumb impressions. His side also relied on long possession, cultivation and payment of land revenue.
Mst. Addan’s side examined Muhammad Soomar, her son and legal heir, who also acted as attorney for other heirs.
The Supreme Court noted the absence of documentary material and confidence-inspiring independent evidence supporting the allegation of fraud. It also found that proper particulars of fraud had not been given.
That difference mattered. A Gift Mutation in Pakistan dispute is harder to win through a later denial when the beneficiary can produce the transaction record, donor statements and possession evidence.
Two Courts Agreed—Then the High Court Reversed Them
The Trial Court dismissed Jumo’s suit and decreed Mst. Addan’s suit to the extent of her claimed 17-paisa share. It directed that she be put in joint possession.
Jumo appealed, but the Additional District Judge dismissed his appeals in 2006.
In revision, the Sindh High Court found that the courts below had failed to decide the framed maintainability issue, including limitation. It treated that omission as a material irregularity, found the fraud allegation unsupported, set aside the lower-court judgments, decreed Jumo’s suit and dismissed Mst. Addan’s suit.
The Supreme Court held that this revisional interference was justified on the record.
The 27-Year Delay: Why Limitation Became Dangerous
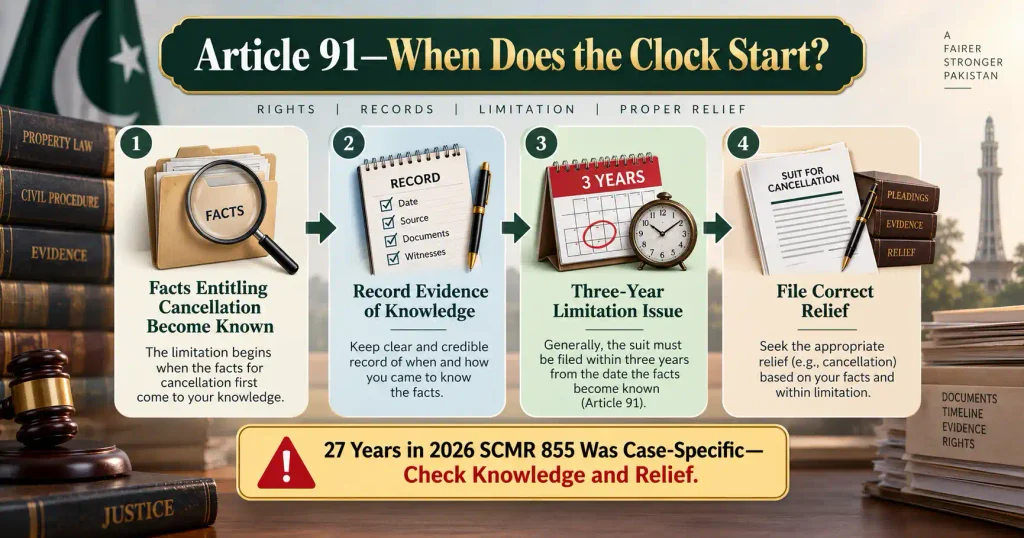
In Gift Mutation in Pakistan, limitation can be decisive. It was central to this result.
The Supreme Court discussed Article 91 of the Limitation Act, 1908. Article 91 provides three years for a suit to cancel or set aside an instrument not otherwise specifically provided for, with time running from when the facts entitling the claimant to cancellation or setting aside become known.
That wording matters. 2026 SCMR 855 is not a rule that every mutation becomes immune three years after entry.
On this record, however, the Supreme Court upheld the High Court’s conclusion that the challenge brought after about 27 years was barred and that the lower courts had wrongly failed to decide limitation.
For a live Gift Mutation in Pakistan dispute, test limitation against the exact relief, applicable article, date of knowledge and evidence of discovery.
Our guide on Limitation in Inheritance Cases in Pakistan explains the wider inheritance context.
Fraud Alleged? Vague Words Will Not Save the Suit
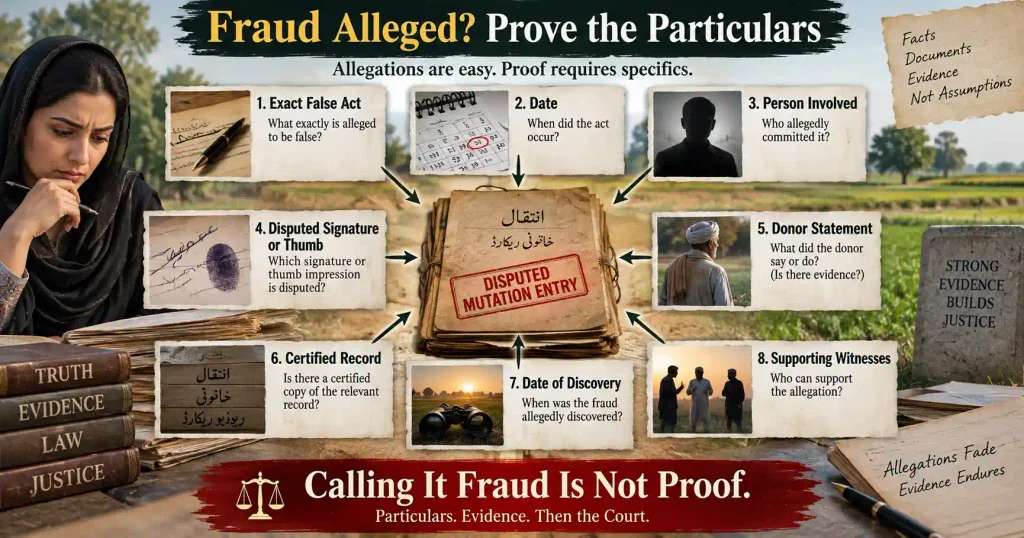
Words such as “bogus,” “illegal,” “collusive” and “fraudulent” are not evidence.
Order VI Rule 4 of the Code of Civil Procedure requires particulars where a party relies on fraud. The Supreme Court stressed that a person alleging fraud must state the material particulars and bring sufficient supporting evidence.
The Court found that Mst. Addan’s side had not done that. The allegations were not supported by convincing material capable of displacing Jumo’s evidence and the official record. The Court reiterated that general allegations of fraud, however strongly worded, are insufficient without specific particulars.
For Gift Mutation in Pakistan, a fraud pleading should identify the alleged false act, disputed entry or document, persons involved, relevant dates, the signature or thumb impression being denied, the date of discovery and the evidence said to prove falsity.
If forgery is alleged, obtain the certified or original record needed for lawful comparison rather than relying on screenshots.
A Muslim Gift Needs More Than a Revenue Entry
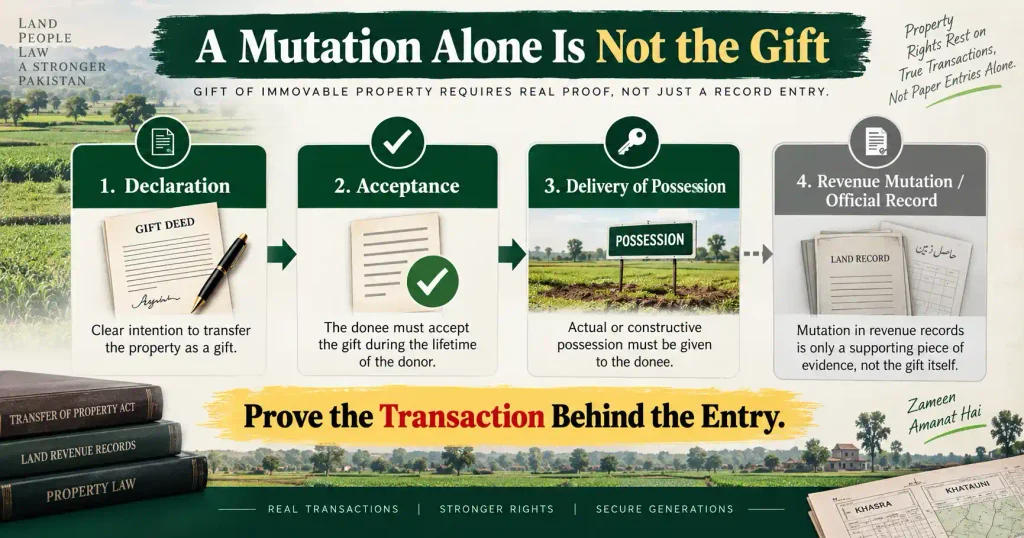
For Gift Mutation in Pakistan, the Supreme Court restated the three classic elements of a completed Muslim gift:
- declaration of gift by the donor;
- acceptance by or on behalf of the donee; and
- delivery of possession.
The Court also explained that acceptance can be express or implied and may be inferred from conduct.
Section 129 of the official Transfer of Property Act, 1882 preserves rules of Muslim law. Accordingly, the statutory chapter on gifts does not override the applicable rules of Muslim law.
“Registration is not always required” does not mean “proof is not required.” For Gift Mutation in Pakistan, documentation can prevent later disputes.
Compare our guides on Valid Gift in Pakistan and Gift Deed in Pakistan.
Declaration: Was There a Real and Voluntary Gift?
The donor must actually make the gift. Courts look for evidence showing a clear and voluntary intention to transfer the property without consideration.
A mutation prepared later cannot create a declaration that never occurred.
Acceptance: Can Conduct Prove It?
Acceptance may be express or implied.
In 2026 SCMR 855, the Supreme Court said acceptance could be inferred from conduct. Jumo’s taking and retaining possession after the gift supported acceptance.
That matters in Gift Mutation in Pakistan because family transactions are not always documented with commercial formality.
Possession: Did Control Really Change?
Delivery of possession is a fundamental ingredient of a completed Muslim gift, subject to the nature of the property and legally recognized circumstances.
Jumo’s long possession, cultivation and payment of land revenue supported the finding that the gift had been acted upon.
If a donor allegedly gifts land but continues exercising exclusive control exactly as before, the court may ask much harder questions about whether the gift was ever completed.
Why Long-Standing Revenue Records Carried Weight
In Gift Mutation in Pakistan, the Supreme Court referred to Article 49 of the official Qanun-e-Shahadat Order, 1984 concerning entries in public or official records made in performance of official duty.
Because the land was situated in Sindh, section 52 of the Sindh Land Revenue Act, 1967 is especially relevant. The provision was substituted in 2022 and states that an entry in a record of rights made in accordance with law is presumed to be true until the contrary is proved or a new entry is lawfully substituted. See the official Sindh Land Revenue amendment.
That presumption is rebuttable, not absolute.
In 2026 SCMR 855, the old entries were reinforced by donor statements and continued possession. The challengers did not produce sufficient evidence to overcome that record.
This is the correct way to understand Gift Mutation in Pakistan: a mutation is not title by itself, but a qualifying long-standing revenue entry may become powerful evidence when the underlying transaction is also proved.
Do Not Read 2026 SCMR 855 Too Broadly
The Supreme Court did not hold that every old gift mutation is valid.
It did not hold that a woman loses inheritance merely because her name disappears from a record.
It did not make fraud impossible to prove.
And it did not convert mutation into a title deed.
The Court decided the record before it. Jumo produced evidence of the transaction and possession; the appellants failed to establish the pleaded fraud and also faced a limitation problem.
That distinction protects both sides: a genuine Gift Mutation in Pakistan should not fall on a bare denial, and a fabricated one should not become valid merely because it is old.
For the opposite situation, see our guide on Inheritance Mutation in Pakistan, where a wrong revenue entry could not by itself extinguish an heir’s lawful right.
Gift Mutation in Pakistan: Build the Evidence File First
Before litigation, collect the full chain of proof: certified mutation, previous and current record of rights, donor statement, donor’s title record, original gift deed if any, related Quboliat Nama or exchange document, possession and cultivation evidence, land-revenue receipts, witness details, earlier applications and notices, and documents showing when the disputed entry was first discovered.
Where signatures or thumb impressions are specifically denied, preserve the record needed for comparison. Where possession is disputed, identify who actually cultivated, controlled or used the property.
A Gift Mutation in Pakistan case should be built from connected evidence, not one photocopy.
Gift Disputed? Choose the Remedy Before Filing
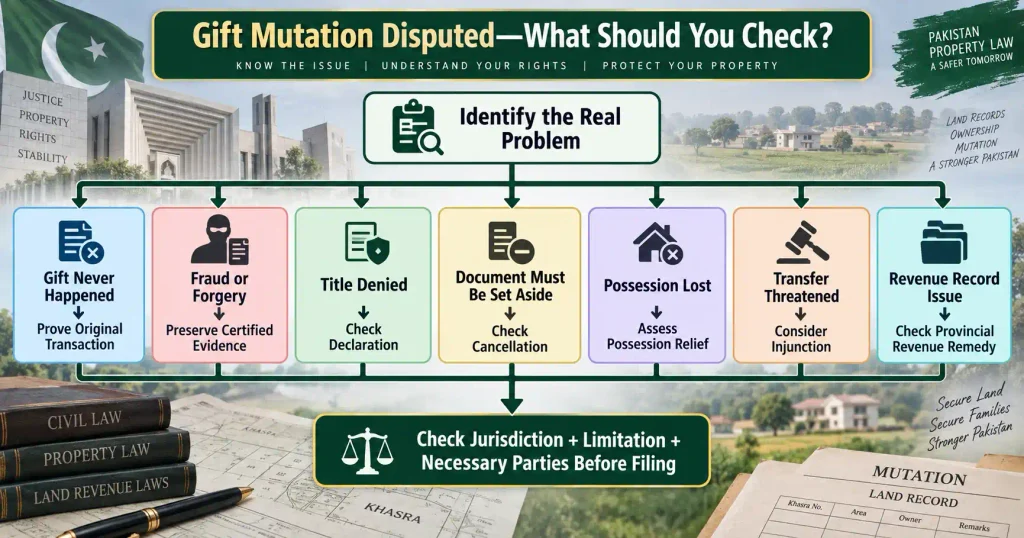
The relief claimed can decide the case.
In 2026 SCMR 855, the High Court’s reasoning—upheld by the Supreme Court—also addressed the problem that the appellant had not sought the necessary consequential cancellation relief against the gift or revenue entries.
Section 42 of the official Specific Relief Act, 1877 contains an important proviso: where a plaintiff is able to seek further relief beyond a mere declaration but omits to do so, the court should not grant the bare declaration.
Depending on the controversy, a claimant may need declaration, cancellation, possession, injunction, mesne profits, revenue correction or another lawful remedy.
Do not copy prayers from another Gift Mutation in Pakistan case; the correct forum and relief depend on the record and province.
Province Matters: Sindh Procedure Is Not Pakistan-Wide
Although the focus keyword is Gift Mutation in Pakistan, 2026 SCMR 855 concerned agricultural land in Khairpur, Sindh.
Mutation procedure, authorities, forms, fees and appellate routes can differ across provinces and territories.
The Supreme Court’s principles on proof, fraud and Muslim gift requirements are broadly important. But Gift Mutation in Pakistan procedure is not uniform: do not copy a Sindh route into Punjab, Khyber Pakhtunkhwa, Balochistan or Islamabad without checking the applicable statute and rules.
This distinction is especially important when preparing documents or deciding whether the real dispute belongs before a revenue authority, civil court or another competent forum.
What the Supreme Court Did—and Did Not Decide
For this Gift Mutation in Pakistan dispute, the Supreme Court dismissed both civil appeals with no order as to costs and maintained the Sindh High Court judgment.
It accepted that the lower courts had failed to decide maintainability and that the appellants had failed to prove fraudulent gift and mutation.
Jumo had discharged the burden through the evidence he produced, so the revenue entries remained operative. The Supreme Court specifically referred to his documents and sworn statement as sufficient to discharge the onus regarding validity of the gift and mutation on this record.
The decision is not a shortcut for every Gift Mutation in Pakistan dispute. It turned on the 1971 record, donor statements, possession, limitation and the failure to plead and prove fraud with specificity.
Before You File: 10 Checks That Can Save Your Case
- Obtain certified copies of the mutation and record of rights.
- Trace the donor’s title before arguing about the gift.
- Identify proof of declaration, acceptance and possession.
- Compare the donor’s recorded statement with the current denial.
- Check who controlled or cultivated the property after the gift.
- Plead fraud with dates, acts, persons and documents.
- Record the exact date and proof of discovery for limitation.
- Identify every consequential relief the dispute requires.
- Confirm civil-court and revenue jurisdiction for the province.
- Preserve originals, certified copies and earlier statements.
These checks cannot guarantee success, but they can prevent a Gift Mutation in Pakistan case from failing because the wrong issue, wrong relief or weak evidence was placed before the court.
Conclusion: Old Gifts Survive on Proof, Not Memory
2026 SCMR 855 is not a judgment saying that old mutations can never be challenged. It is a judgment about proof, pleadings and limitation.
Jumo’s case was supported by official record, donor statements, possession and conduct. The challengers alleged fraud but failed to provide the particulars and convincing evidence needed to establish it. The lower courts also failed to properly decide limitation.
The safest rule for Gift Mutation in Pakistan is to look beyond the entry. Ask whether the donor owned the property, the gift was declared and accepted, possession was delivered, fraud is proved, limitation is satisfied and the correct relief has been sought.
A family memory can change. A properly proved legal transaction is much harder to erase.
FAQs: What People Ask Before a Gift Dispute
Is Gift Mutation in Pakistan final proof of ownership?
No. A mutation is relevant revenue evidence but is not, by itself, a title deed. A court may examine the donor’s title, original gift, declaration, acceptance, possession and supporting evidence. In 2026 SCMR 855, the entry survived because donor statements, possession and other evidence supported the transaction while fraud was not proved.
Can an old gift mutation still be cancelled?
Yes, depending on the facts and limitation law. Age alone does not make a false transaction valid. But delay can become a serious obstacle. Article 91 provides three years for cancellation of an instrument from the relevant knowledge point. The exact relief, knowledge date and supporting evidence must therefore be examined.
What did 2026 SCMR 855 actually decide?
The Supreme Court dismissed the appeals and maintained the Sindh High Court judgment. It found no basis to disturb the conclusion that the challengers failed to establish fraudulent gift and mutation. Limitation, specific pleading of fraud, possession and the long-standing revenue record were all important to the result.
Can a sister gift her inherited share to a brother?
Yes. An adult owner may generally gift her lawful share if the transaction is voluntary and legally complete. A Muslim gift requires declaration, acceptance and delivery of possession. If the alleged gift is disputed, the beneficiary must prove the transaction through legally sufficient evidence rather than relying only on a family assertion.
Does an oral Muslim gift require registration?
Not necessarily. Section 129 of the Transfer of Property Act preserves Muslim law, and a completed Muslim gift may be oral where declaration, acceptance and delivery of possession are proved. Documentation remains highly valuable because later litigation may turn on whether those ingredients can actually be established.
How do I prove fraud in a gift mutation?
State the specific fraud, dates, persons involved, disputed act or document and supporting evidence. Preserve certified revenue records and originals needed for comparison. Vague expressions such as “bogus” or “fraudulent” are not enough. The court needs specific pleaded facts and convincing evidence.
Which forum handles a gift mutation dispute?
It depends on the real issue and province. A title, fraud, cancellation or possession dispute may require civil-court relief, while a limited revenue-record issue may involve revenue authorities. Do not assume one forum fits every Gift Mutation in Pakistan dispute. Jurisdiction should be checked before filing.
What should I collect before challenging a gift mutation?
Start with certified mutation and record-of-rights copies, the donor’s statement and title record, possession and cultivation evidence, revenue receipts, any gift deed or related document, witness details, earlier applications and proof of when the disputed entry was discovered. Then check limitation and identify the precise relief required.
Legal Disclaimer: Read This Before Acting
This article is for general legal awareness only and does not create a lawyer-client relationship. Property disputes depend on the province, title chain, pleadings, documents, possession, limitation and relief claimed. A qualified lawyer should examine the complete certified record before any Gift Mutation in Pakistan case is filed or defended.