A tax return can look complete when filed and still become difficult months later when FBR asks one question: “Can you prove this figure?” The Income Tax Ordinance 2001 is Pakistan’s main federal income-tax law, but understanding it requires more than copying a rate or section number from an old website.
This guide explains the latest law, official PDF, key sections, five heads of income, return and wealth-statement duties, ATL status, FBR notices, section 111, appeals, evidence and major Finance Act 2026 changes. The aim is simple: understand the rule before a filing, transaction or notice becomes a costly dispute.
For most Pakistani taxpayers, the Income Tax Ordinance becomes important when filing a return, explaining assets or responding to an FBR notice.
Table of Contents
Income Tax Ordinance 2001 at a Glance
| Point | Current Position |
|---|---|
| Main law | Income Tax Ordinance, 2001 |
| Federal tax authority | Federal Board of Revenue (FBR) |
| Latest FBR consolidated text | Amended up to 30 June 2026 |
| Major annual amendment | Finance Act 2026 |
| Return provision | Section 114 |
| Wealth statement | Section 116 |
| Deemed assessment | Section 120 |
| Amendment of assessment | Section 122 |
| Unexplained income/assets | Section 111 |
| Record retention | Section 174 |
| Audit | Section 177 |
| Appeals | Sections 127, 131 and 133 |
The Income Tax Ordinance 2001 was promulgated in 2001 and came into operation from 1 July 2002. Since then, Finance Acts and other amendments have repeatedly changed rates, procedures and taxpayer obligations. An older PDF may therefore look official while no longer stating the current law.
Latest Income Tax Ordinance 2001 PDF: Use Official Text
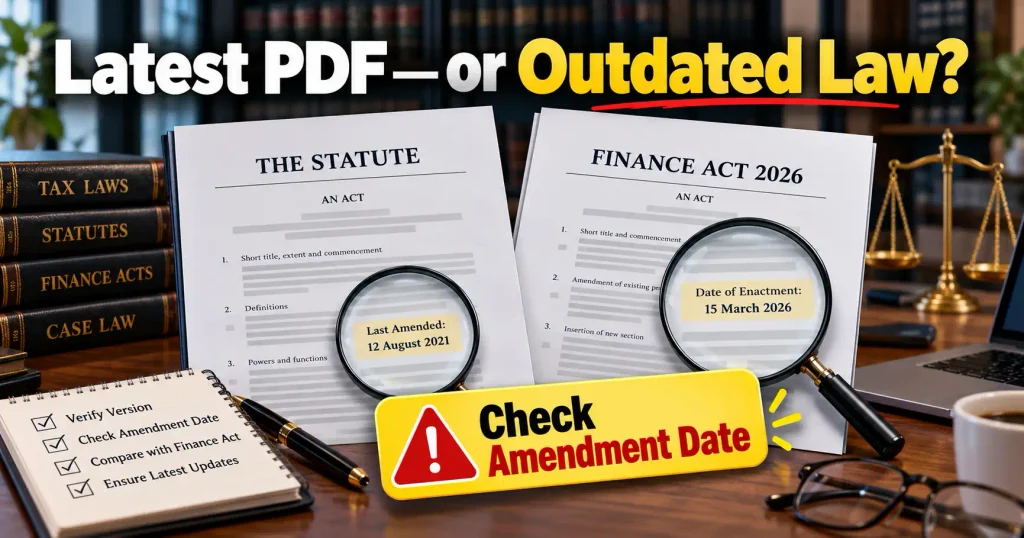
If you searched income tax ordinance 2001 pdf, start with FBR rather than a copied file on a private website. FBR currently lists the consolidated Income Tax Ordinance 2001 amended up to 30 June 2026, together with earlier versions. This helps when a past tax year needs a different version of the law. Official FBR Income Tax Ordinance collection FBR
People also search income tax ordinance 2001 pdf free download. The safest free copy is the official FBR document. Searches for fbr income tax ordinance usually have the same intent: finding the authoritative FBR version rather than a private mirror. Check its amendment date and then confirm whether a later Finance Act, SRO, rule or binding judgment affects the issue you are researching.
Always check the amendment date before relying on any Income Tax Ordinance PDF available online.
The same caution applies to income tax ordinance 2001 study notes. Notes can explain concepts, but they are not the law. The official Income Tax Ordinance 2001 should remain your primary reference for a return, notice, appeal or property transaction.
What Does the Income Tax Ordinance 2001 Actually Do?
The Income Tax Ordinance 2001 does much more than set annual rates. It determines taxable income, income classification, deductions, filing duties, withholding and advance tax, records, audit, assessment, recovery and appellate remedies.
Read tax law in layers. The Ordinance contains substantive and procedural provisions; its Schedules contain many rates and exemptions; the Income Tax Rules deal with procedure; Finance Acts amend the law; SROs and notifications operate within delegated authority; and FBR circulars explain the department’s view. Binding court judgments control legal interpretation where applicable.
A circular may help explain a change, but it cannot rewrite an Act of Parliament or override a binding judgment.
A Practical Map Before You Search a Section
| Your question | Start with | Why it matters |
|---|---|---|
| Total income and classification | Sections 9–11 | The correct head affects computation |
| Salary | Sections 12 onward | Salary has specific inclusion rules |
| Property income | Sections 15 onward | Rent has separate rules |
| Business income | Sections 18 onward | Deductions and records matter |
| Capital gains | Section 37 and related law | Asset and disposal date matter |
| Other sources | Section 39 | Residual income may fall here |
| Unexplained money/assets | Section 111 | Source and evidence may be questioned |
| Return and wealth statement | Sections 114 and 116 | Filing and reconciliation duties |
| Assessment | Sections 120 and 122 | Filing and amendment consequences |
| Appeals | Sections 127, 131 and 133 | Forum and limitation are critical |
| Records and audit | Sections 174 and 177 | Evidence may be demanded later |
This is a navigation guide, not a substitute for the full Income Tax Ordinance 2001. Definitions, provisos, Schedules, amendment history and the relevant tax year can change the answer.
Finance Act 2026 Changed More Than Tax Rates
The Income Tax Ordinance 2001 should now be read with Finance Act 2026 and the consolidated text amended up to 30 June 2026. FBR later issued Circular No. 02 of 2026-27 on 8 September 2026 explaining important income-tax amendments. The circular is guidance; the enacted text remains the legal starting point.
Among the important changes, section 7E was omitted. For the framework effective from 1 July 2026, the First Schedule provides a flat 2.75% advance-tax rate under section 236C for an ATL seller and 1.25% under section 236K for an ATL buyer. Non-ATL treatment can be materially higher under the Tenth Schedule, so a property rate should never be quoted without checking taxpayer status and the applicable year.
Finance Act 2026 also changed salary taxation, foreign-card remittances, digital or social-media income and other withholding provisions. Do not automatically apply a 2026 amendment to an earlier year. First identify the relevant tax year and the effective date of the amendment.
Five Heads of Income Can Change the Tax Result
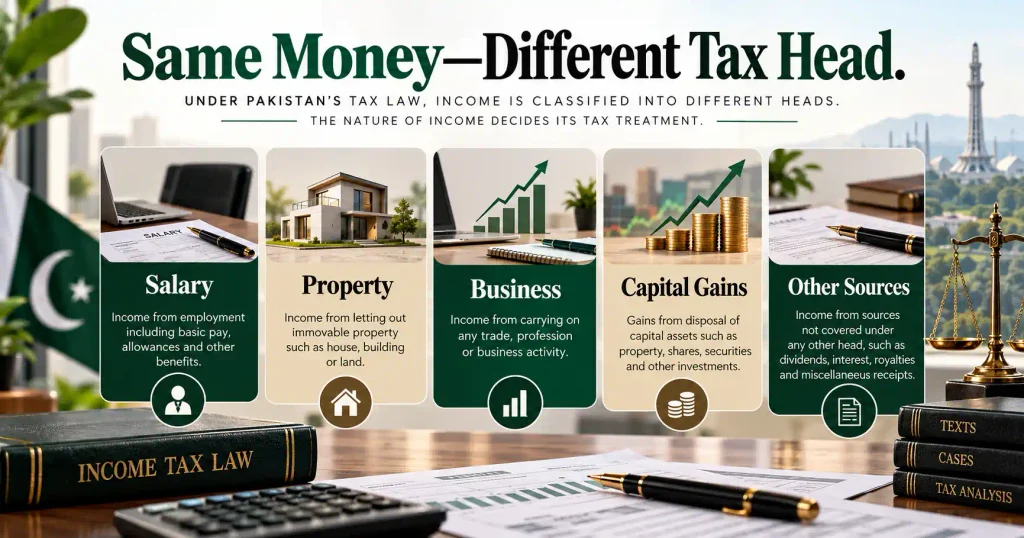
Section 11 classifies income under five heads. The label matters because computation, deductions, withholding and proof may differ.
Salary: Reconcile More Than the Bank Credit
Salary can include more than cash credited to an employee’s account. Allowances, benefits and perquisites may matter under the applicable law. Keep the salary certificate, withholding evidence, bank record and return consistent.
Property: Section 7E Is Gone, Rent Is Not
The omission of section 7E does not abolish ordinary taxation of actual property income. Rental income remains a separate head under the Income Tax Ordinance 2001, while capital gains and transfer-related advance taxes are governed separately.
Business: Expense Proof Can Decide the Case
A business taxpayer should connect declared receipts, expenses and assets with books, invoices, contracts, bank records and other reliable evidence. An expense may sound reasonable yet still fail if its occurrence or deductibility cannot be proved.
Capital Gains: Asset and Date Matter
Capital-gains treatment can depend on the asset, acquisition and disposal dates, exemptions and the law then in force. Preserve acquisition documents, transfer instruments, payment evidence and the ownership chronology.
Other Sources: The Residual Head Still Matters
Income that does not properly fall under salary, property, business or capital gains may fall under “Income from Other Sources.” Classification should follow the law and facts, not whichever label produces the lowest tax.
Return, Wealth Statement and ATL Are Not the Same
Registration, return filing and ATL status are different. An NTN or CNIC-linked registration identifies a taxpayer. A return under section 114 reports income and tax information. A wealth statement under section 116, where required, records assets, liabilities, expenditure and prescribed particulars. ATL status is a separate legal and administrative status.
That is why a person may have an NTN but still need to confirm that the return was actually filed and that the person currently appears on ATL. Verify registration through our Online NTN Verification by CNIC guide and use the FBR NTN Certificate guide when formal proof of registration is needed.
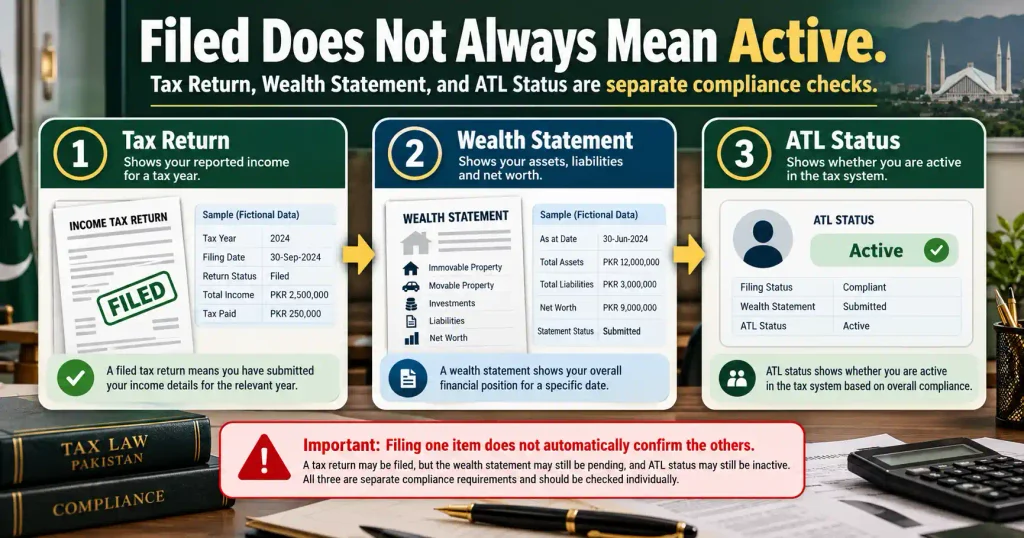
For filing steps, see our FBR Tax Return guide. The Income Tax Ordinance 2001 provides the legal framework, but IRIS procedures and deadline extensions can change. As of 7 October 2026, FBR Circular No. 3 of 2026-27 has extended the Tax Year 2026 filing date to 15 October 2026 for persons whose return was otherwise due on 30 September 2026. Official FBR deadline extension circular .
Wealth Reconciliation Can Expose a Hidden Problem
A return may declare income correctly while the wealth statement still fails to explain increased assets or personal expenses. Opening wealth, income, exempt receipts, genuine gifts or loans, expenditure and closing wealth should reconcile on evidence.
Never invent a gift, loan or cash balance merely to force the statement to balance.
Received an FBR Notice? Read the Section First
A notice is not automatically a final tax demand. It may seek information, require a return, raise a discrepancy or propose another statutory step. First identify the section invoked.
Check the tax year, service date, response deadline, issuing authority, allegation and documents demanded. Download the notice from the official IRIS account rather than relying only on a forwarded screenshot.
Then build an evidence file containing the notice, return, wealth statement, bank records, contracts, invoices, property documents, tax-payment evidence, withholding certificates and prior correspondence. A short reply supported by primary evidence is usually stronger than a long unsupported narrative.
Section 111: A Label Is Not Proof
Section 111 is a sensitive part of the Income Tax Ordinance 2001 because unexplained money, investment, expenditure or assets may have serious consequences if the taxpayer cannot satisfactorily explain the nature and source under the law.
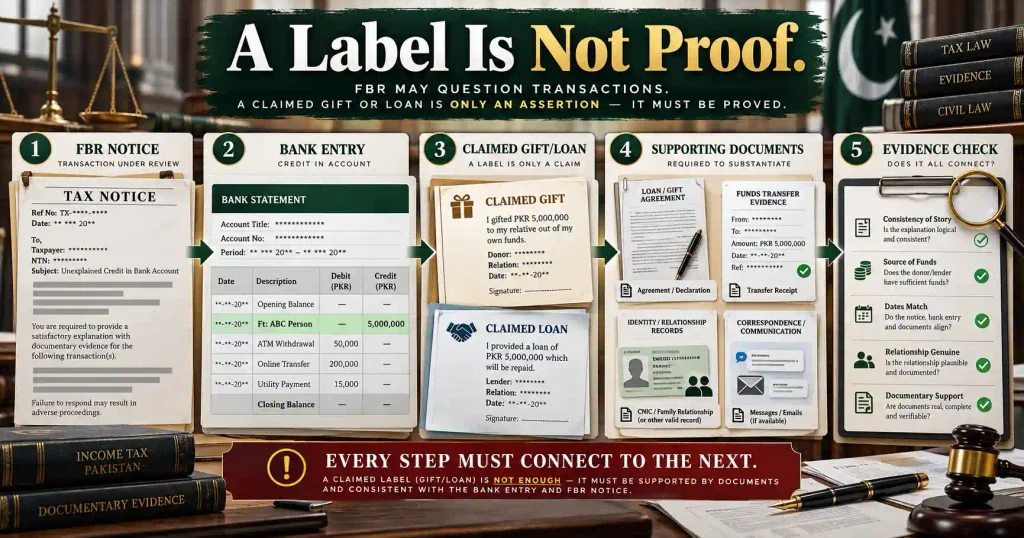
If an amount is a gift, preserve donor identity, relationship, transaction trail and relevant capacity evidence. For a loan, keep the agreement, lender details, banking trail and repayment terms. For inheritance, preserve succession and transfer documents connecting the asset to the beneficiary.
A bank entry proves movement of money. It does not automatically prove the legal explanation for that movement.
Audit, Assessment and Demand Are Different Stages
Audit, assessment and recovery are not the same process. Section 177 deals with audit, while assessment or amendment involves separate provisions and safeguards.
Ask whether FBR is merely seeking records, proposing an adverse view, passing an assessment order or recovering an existing demand. The response and remedy can change at each stage.
Do not file an appeal simply because a notice feels unfair; first check whether it is an appealable order. But do not ignore an order because earlier correspondence was only a notice.
Appeals: Check the Forum Before Time Runs Out
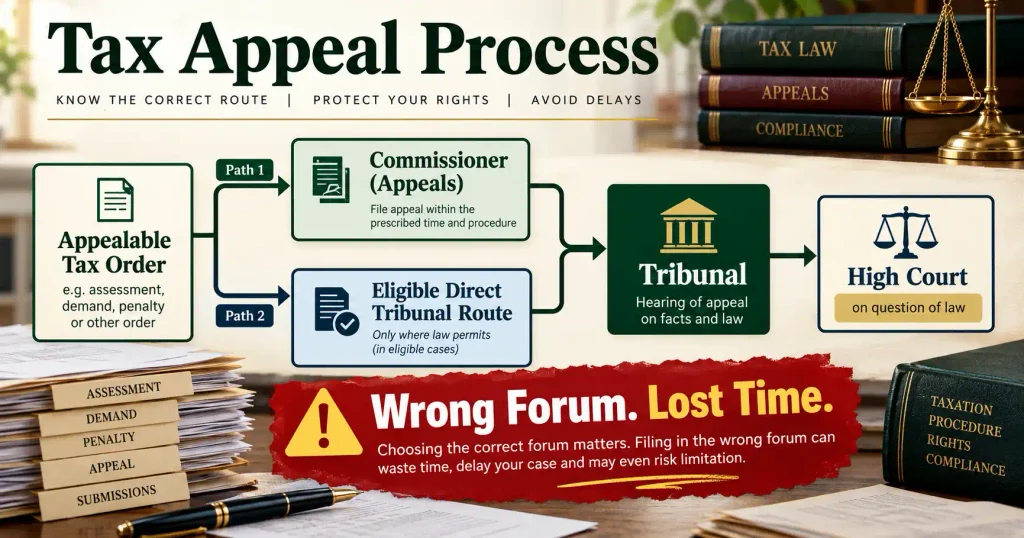
The Income Tax Ordinance 2001 provides statutory appeals, but the correct forum depends on the order and current law. Section 127 governs appeals to the Commissioner Inland Revenue (Appeals). Current law also permits an eligible aggrieved taxpayer, for matters covered by section 127, to surrender that first appellate remedy and move directly to the Appellate Tribunal Inland Revenue.
Where the Commissioner (Appeals) route applies, FBR’s published guidance states a 30-day period from receipt of the relevant demand notice or order. Section 131 also uses a 30-day period for an appeal to the Tribunal, while section 133 currently provides 60 days from communication of the Tribunal order for a High Court reference on a question of law.
Older material built around section 126A’s former pecuniary-jurisdiction regime can mislead readers because section 126A was omitted by Finance Act 2025. Record the service date and preserve proof of receipt. A good merits case can still be harmed by filing in the wrong forum or outside limitation.
Complaint, ADR and Appeal Serve Different Purposes
A complaint about maladministration is not automatically a substitute for a statutory appeal against tax liability or an appealable order. Likewise, filing a complaint does not necessarily stop an appeal deadline. Protect limitation first and identify whether a stay of recovery is also required.
The Ordinance also provides an Alternative Dispute Resolution mechanism for qualifying disputes. Before using ADR, check eligibility, the stage of proceedings, any pending appeal or reference, and the legal effect on other remedies. Settlement should be a deliberate legal choice, not an attempt to bypass procedure.
Six-Year Records Rule Has an Important Exception
Section 174 generally requires prescribed records to be retained for six years after the end of the relevant tax year. The Income Tax Ordinance 2001, however, contains an important exception where proceedings remain pending.
In Commissioner Inland Revenue, Lahore and others v. Salman Butt and others, 2025 SCP 173, the Supreme Court considered section 174(3). FBR’s official case-law summary records that the Court upheld the department’s appeal, set aside the contrary High Court decision and held that records may be required beyond the ordinary six-year period where relevant proceedings are still pending.
The Court did not hold that FBR may demand records forever in every case; the point was the statutory exception for pending proceedings. The practical rule is to check for any pending assessment, appeal, revision, reference, petition, prosecution or other covered proceeding before destroying older records.
Faceless Tax Administration Changes How You Prepare
On 25 September 2026, FBR announced the National Faceless Centre in Islamabad. FBR said audit and assessment cases would be selected through a computerized risk-based system, automatically allocated, and separated among audit, assessment and quality-review functions. Notices, replies and hearings are intended to take place electronically through IRIS, with field action where legally required.
FBR’s current updates also list electronic-scrutiny measures and final rules concerning faceless audit and assessment. Clean digital evidence therefore matters more: keep IRIS contact details current, preserve acknowledgements and upload readable, clearly labelled documents on time.
Costly Mistakes to Avoid Before FBR Finds Them
The Income Tax Ordinance 2001 is easier to manage when evidence exists before a dispute. Common mistakes include:
- treating NTN registration as proof of ATL status;
- filing without reconciling the wealth statement;
- calling a bank credit a gift or loan without proof;
- using an old rate for a new tax year;
- applying Finance Act 2026 retrospectively without legal basis;
- ignoring the Tenth Schedule where ATL status matters;
- destroying records after six years despite pending proceedings;
- replying without checking the section and deadline;
- confusing an audit notice with a final demand; and
- using a private PDF when FBR has a newer official version.
For super-tax issues, see our Super Tax Adjustment guide rather than assuming every deduction or collection can be adjusted in the same manner.
Practical Check Before You Rely on a Tax Answer
Before a filing, payment, appeal or major transaction under the Income Tax Ordinance 2001, verify the tax year, the statutory text applicable to that year, the exact section and Schedule, the taxpayer’s ATL status where relevant, and the evidence supporting the factual claim.
Then ask: If FBR questions this two years from now, what document will prove it?
That simple question often reveals a weak position before the department does.
Frequently Asked Questions About Income Tax Ordinance 2001
1. What is the Income Tax Ordinance 2001?
The Income Tax Ordinance 2001 is Pakistan’s principal federal income-tax statute. It covers taxable income, returns, assessments, withholding and advance tax, records, audit, recovery and appellate remedies. It must be read with its Schedules, the Income Tax Rules, later Finance Acts, valid notifications and binding judgments applicable to the relevant tax year.
2. Where can I get the latest Income Tax Ordinance 2001 PDF?
Use FBR’s official Income Tax Ordinance page. FBR currently lists the consolidated text amended up to 30 June 2026 and older versions. If the income tax ordinance 2001 pdf is needed for a past dispute, do not automatically use the newest version; identify the law applicable to the tax year or transaction in question.
3. Did Finance Act 2026 remove section 7E?
Yes. Finance Act 2026 omitted section 7E. That does not remove ordinary rental-income taxation, capital gains or advance tax under sections 236C and 236K. Older periods or pending disputes may still require year-specific analysis rather than a blanket assumption about previous liabilities or possible refunds.
4. Does having an NTN mean I am an active filer?
No. NTN registration and ATL status are different. Registration identifies the taxpayer, while ATL is a separate status under the current framework. Check ATL separately, especially before property, banking or other transactions where non-ATL withholding may be substantially higher.
5. What should I do first after receiving an FBR notice?
Read the whole notice and identify the section, tax year, allegation, documents required, date of service and response deadline. Download it from IRIS, preserve a copy and organize evidence before replying. Do not assume the notice is a final assessment or that it is immediately appealable.
6. How can I explain an amount questioned under section 111?
Start with the genuine source and prove it. For a loan, preserve lender identity, agreement, banking trail and repayment terms. For a gift, keep donor details and transaction evidence. For inheritance, preserve succession and transfer records. A label in the wealth statement is not enough if the evidence does not support it.
7. How long must tax records be kept in Pakistan?
Section 174 generally uses a six-year period, but records may need to be retained longer where relevant proceedings remain pending. The Supreme Court decision reported as 2025 SCP 173 confirms the importance of this exception. Check for pending proceedings before destroying older records.
8. Can I appeal directly to the Appellate Tribunal?
Current section 127 allows an eligible aggrieved taxpayer, in an appealable matter covered by that provision, either to use the Commissioner (Appeals) route or surrender that first appeal and move to the Appellate Tribunal Inland Revenue. Verify the order, forum and limitation before filing.
Conclusion: Read the Law Before a Notice Becomes a Crisis
The Income Tax Ordinance 2001 determines how income is classified, what must be filed, what FBR may question, what evidence should be retained and which remedy is available when a dispute begins.
The Income Tax Ordinance should always be read with the law applicable to the relevant tax year.
Use the latest official text, separate Tax Year 2026 filing issues from rules effective from 1 July 2026, check ATL status where transaction-based withholding depends on it, and create evidence before a notice arrives. The strongest tax position is not the longest reply; it is the one that can be proved.
Disclaimer: This article provides general legal and tax information for Pakistan and was reviewed against official material available on 7 October 2026. It is not personalised tax, accounting or legal advice. Tax rates, filing dates, rules, SROs and judicial interpretations can change. For a material transaction, assessment, appeal or dispute, verify the law applicable to the relevant tax year and obtain professional advice where appropriate.